
Tax Planning
Salary or Dividends from a UK LTD: The Optimal Strategy for Non-Residents in 2026
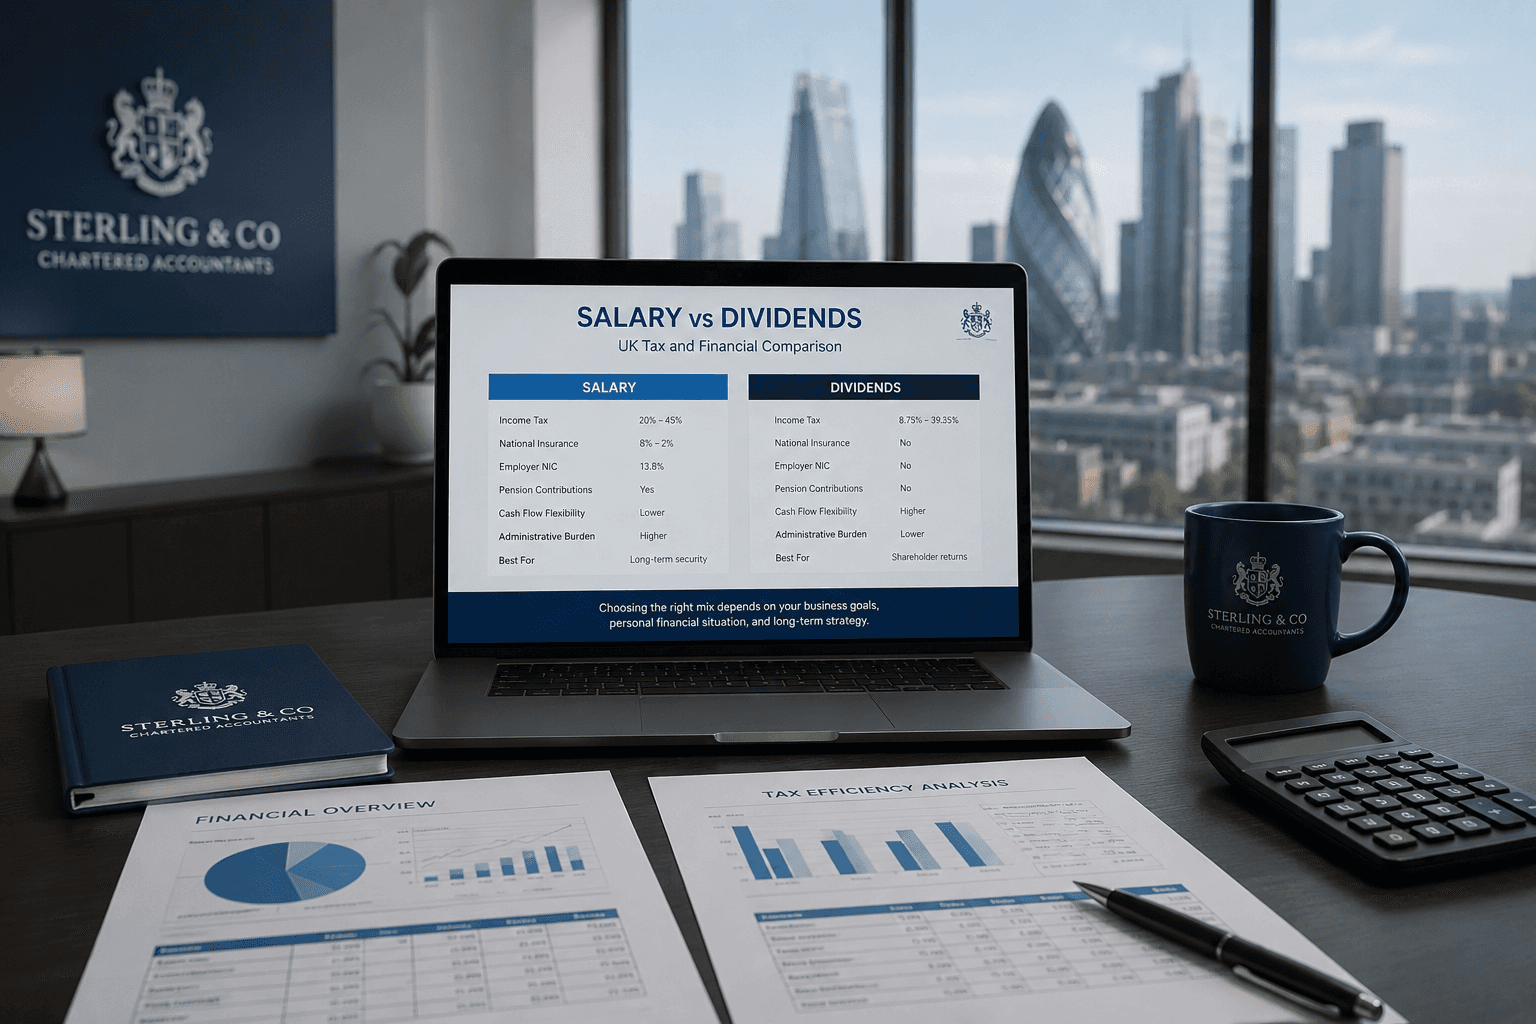
The combination of salary and dividends is the most effective strategy for extracting profits from a UK LTD in a tax-efficient manner. Discover the rates updated to 2026, the optimal structure for a non-resident director and how Italian tax residency changes the calculation.
For the director of a UK LTD, deciding how to extract profits from the company is the most immediate tax planning decision with the greatest impact on the overall tax burden. The choice is not binary — salary or dividends — but concerns the optimal calibration of a combined structure that minimises National Insurance contributions, reduces Corporation Tax and optimises personal taxation.
In 2026, with the Dividend Allowance reduced to just £500 and Income Tax and Dividend Tax rates unchanged, the optimal structure for a non-resident director requires a precise calculation that also takes into account the Italian tax framework — because dividends received from a UK LTD by an Italian resident are not only subject to British rules, but also to the Italian substitute tax of 26%.
How salary taxation works in 2026
The salary paid to the director by their LTD is treated for tax purposes as employment income. It has two simultaneous effects: it is deductible from company profits — reducing the taxable base for Corporation Tax purposes — and it is subject to personal taxation via Income Tax and National Insurance.
Income Tax rates 2026 for UK residents:
- 0% — Personal Allowance: up to £12,570
- 20% — Basic Rate: £12,571 to £50,270
- 40% — Higher Rate: £50,271 to £125,140
- 45% — Additional Rate: above £125,140
National Insurance 2026:
Employee NI contributions (Class 1):
- 0% up to £12,570 (Primary Threshold)
- 8% between £12,571 and £50,270
- 2% above £50,270
Employer NI contributions (Class 1):
- 0% up to £9,100 (Secondary Threshold)
- 13.8% above £9,100
Employer NI contributions are deductible from Corporation Tax — meaning this cost also reduces the company's taxable profit.
The critical point: unlike Income Tax — where the £12,570 Personal Allowance protects the first £12,570 of salary from any taxation — employee NI contributions kick in above £12,570, and employer NI contributions above £9,100. This makes salary relatively expensive compared to dividends at lower income levels.
How dividend taxation works in 2026
Dividends are distributed from company profits after the payment of Corporation Tax — they are not deductible. However they are taxed at personal rates significantly lower than salary and are not subject to National Insurance.
Dividend Allowance 2026: £500
The first £500 of dividends received in the tax year are exempt from personal taxation. This threshold was drastically reduced from £2,000 (in 2022) to £1,000 (2023) and then to £500 (from 2023–2024 onwards) — an 85% reduction in two years that has significantly reduced the tax advantage of dividends for small company directors.
Dividend Tax rates 2026:
- 0% — Dividend Allowance: first £500
- 8.75% — Basic Rate: total income up to £50,270
- 33.75% — Higher Rate: total income between £50,271 and £125,140
- 39.35% — Additional Rate: total income above £125,140
Dividends are not subject to National Insurance — neither for the director nor for the company. This is the primary advantage over salary.
Direct comparison: salary vs dividends on equivalent amounts
To make the comparison concrete, here is what happens when £30,000 is taken as salary versus distributed as dividends, for a director with total income below the Higher Rate threshold:
Option A — £30,000 as salary:
- Income Tax: (£30,000 − £12,570) × 20% = £3,486
- Employee NI: (£30,000 − £12,570) × 8% = £1,394
- Employer NI: (£30,000 − £9,100) × 13.8% = £2,884 (borne by company, CT deductible)
- Total cost to company: £32,884
- Net in director's pocket: £25,120
Option B — £30,000 as dividends (from net profit after CT at 19%):
- Corporation Tax paid by company on profit: £30,000 × 19% = £5,700
- Net profit available for dividends: £24,300
- Dividend Tax on director: (£24,300 − £500) × 8.75% = £2,083
- Net in director's pocket: £22,217
In this simplified example, the net salary is higher than net dividends because the CT deductibility of salary partially compensates for the weight of NI and Income Tax. The optimal structure is never just one of the two options: it is the calibrated combination.
The optimal structure for a non-resident director in 2026
For a UK LTD director tax resident in Italy, the most efficient remuneration structure in 2026 is typically as follows:
Component 1 — Salary: £9,100 per year
The salary is set exactly at the employer NI threshold (Secondary Threshold: £9,100). This amount is:
- Deductible from company profits → reduces Corporation Tax
- Below the employee NI threshold (£12,570) → zero NI contributions for the director
- Below the employer NI threshold (£9,100) → zero NI contributions for the company
- Below the Personal Allowance (£12,570) → zero personal Income Tax
Result: £9,100 extracted from the company at virtually zero tax cost for both parties.
Component 2 — Employer pension contributions
The company makes contributions to a registered pension scheme on behalf of the director. Contributions are:
- Fully deductible from Corporation Tax (no absolute upper limit)
- Not subject to NI for either the company or the director
- Not taxed as personal income in the year of contribution
For a director with significant company profits, making £20,000–£40,000 of annual employer pension contributions is the most efficient deduction available — a CT saving of 19%–25% on the amount contributed.
Component 3 — Dividends for the remainder
The remaining profit after salary, pension contributions and Corporation Tax is distributed as dividends. With total income (salary plus dividends) below £50,270, the Dividend Tax rate is 8.75% — well below the Income Tax and NI rates applicable to an equivalent salary.
The impact of Italian residency: dividend taxation in Italy
For a director tax resident in Italy, the taxation of dividends received from a UK LTD does not end in the United Kingdom. The Italian framework adds a further level.
UK withholding tax on dividends to non-resident individuals:
The United Kingdom does not apply withholding tax on dividends distributed by UK companies to non-resident individual shareholders. This is a significant advantage: dividends reach the Italian director gross, with no UK deduction.
Taxation in Italy:
Foreign-source dividends received by individuals resident in Italy who hold shares outside a business regime are subject to a 26% substitute tax applied to the gross dividend — on a final basis, without further reporting obligations if a bank or intermediary applies the withholding, or via tax return (section RL) if dividends are received directly.
The complete calculation for an Italian resident:
Example: UK company with £80,000 of profits. Optimal structure:
- Director salary: £9,100 → zero CT cost, net £9,100
- Employer pension contributions: £20,000 → CT saving: £3,800 (at 19%)
- Remaining taxable profit: £80,000 − £9,100 − £20,000 = £50,900
- Corporation Tax at 19% (small profits + marginal): approx. £9,671
- Net distributable profit: £50,900 − £9,671 = £41,229
- Dividends distributed: £41,229
- Italian substitute tax at 26%: £10,720
- Net in pocket after all taxes: £30,509 + £9,100 (salary) = £39,609
On £80,000 of gross profits the director takes home £39,609 net — an overall effective rate of 50.5% which includes UK Corporation Tax and Italian substitute tax. Without the optimal structure (for example with a higher salary and unused pension contributions) the burden would be significantly higher.
When it makes sense to increase salary above £9,100
There are situations where increasing salary above the minimum threshold is worthwhile:
To build UK National Insurance contributions
NI contributions paid give entitlement to the British State Pension and other UK welfare benefits. A director who intends to reside or work in the United Kingdom in the long term might consider a salary up to £12,570 to accumulate NI qualifying years.
To access mortgages and financing
British and Italian banks assess declared income for credit access purposes. A director with a declared salary of £9,100 has very low employment income on record. In anticipation of a mortgage application, it may be worth temporarily increasing salary to improve the credit profile.
To maximise personal pension contributions
Personal pension contributions (unlike employer contributions) are subject to the limit of 100% of annual remuneration or £60,000, whichever is lower. A director with a salary of £9,100 can only make additional personal contributions up to £9,100. To maximise pension scheme contributions, increasing salary may be worthwhile.
Common mistakes to avoid
- Distributing all profits as dividends without making employer pension contributions — missing the most effective CT deduction available
- Failing to review the salary/dividend structure each tax year in line with profit levels — the optimal structure changes as profits and rates change
- Ignoring the Italian 26% substitute tax when calculating the net return on dividends — leads to overestimating the dividend advantage for Italian residents
- Distributing dividends from profits not yet earned or from insufficient reserves — a dividend distributed in the absence of available profits is unlawful under UK law
- Failing to keep personal and company financial flows separate — informal withdrawals not formalised as salary or dividends may be reclassified as a director's loan with significant tax consequences
FAQ
What is the main difference between salary and dividends for a UK LTD director?
Salary is deductible from company profits (reducing Corporation Tax) but is subject to Income Tax and National Insurance. Dividends are distributed from net profit after Corporation Tax (not deductible) but are taxed at lower personal rates and are not subject to NI. The optimal structure combines both in proportions calibrated to the director's profit levels and tax residency.
What is the optimal salary for a UK LTD director in 2026?
For most directors of small LTDs, the optimal salary in 2026 is £9,100 per year — exactly at the employer NI threshold (Secondary Threshold). At this level the salary is CT deductible, generates no NI for either the director or the company, and generates no personal Income Tax (below the £12,570 Personal Allowance). It is the point of maximum tax efficiency for the salary component.
Are dividends from a UK LTD taxed in Italy for an Italian resident?
Yes. The United Kingdom does not apply withholding tax on dividends distributed to non-resident individual shareholders. In Italy, foreign-source dividends are subject to 26% substitute tax on the gross dividend — on a final basis. This means that the net return calculation for dividends must always include the Italian 26%, not just the UK rates.
How much can I contribute as employer pension contributions from my UK LTD?
There is no absolute limit on employer pension contributions deductible from Corporation Tax, provided they are commercially justified and proportionate to the director's remuneration. However, the total contributions to the pension scheme (employer plus personal) must not exceed the beneficiary's Annual Allowance — equal to £60,000 in 2026, or 100% of annual remuneration if lower.
Can I distribute dividends if my UK LTD is making a loss?
No. Dividends can only be distributed from distributable profits — that is, accumulated net profits after tax as shown in the accounts. Distributing dividends in the absence of available profits is unlawful under British law and may expose the director to personal liability for repayment of the irregularly distributed amounts.